On 18 November 2026, the National Association of REALTORS reported that pending home sales fell 4.7% in October, to a Pending Home Sales Index reading of 63.0, the lowest since the series began in 2001. It is the second straight month of record lows after 66.0 in September, and signings are down 16.7% from a year ago.
Last week, the same association reported closed home sales at a 3.75 million annual pace in October, the lowest since 2010. This report covers contracts signed, which usually close in one to two months. Both point the same way: very few Americans are buying homes right now.
The short answer
Contract signings fell to a record low in October because mortgage rates stayed high, averaging 7.33% for a 30-year fixed loan. The index reading of 63.0 means contract activity is 37% below the average level of 2001, the year the index is based on. Every region fell; the West fell hardest, down 6.9% in a month and 20.3% in a year.
Quick decision guide:
- Buying now? You have more room to negotiate, but rates near 7% plus mean the monthly payment is the number to check first.
- Selling? Expect a slow market: the typical home took 35 days to sell in October, and the pipeline of new contracts is the thinnest on record.
- Waiting for prices to fall? Nothing here points to a price crash; closed-sale prices were still up from a year ago.
- Saving for a down payment? Keep saving. The rate moves the payment, but the down payment is the part you control.
What the October report says
The fall was worse than economists expected: Reuters-polled economists had forecast a 2.0% drop, and the actual fall was 4.7%, more than double that. September was revised from 66.0 to 66.1, already a record low at the time. October broke it again.
All four regions fell on both measures. The Northeast fell least, down 0.8% in a month and 11.1% in a year. The Midwest fell 2.7% and 14.0%, the South 6.3% and 18.7%. The West fell hardest, down 6.9% and 20.3%, to an index reading of 45.8.
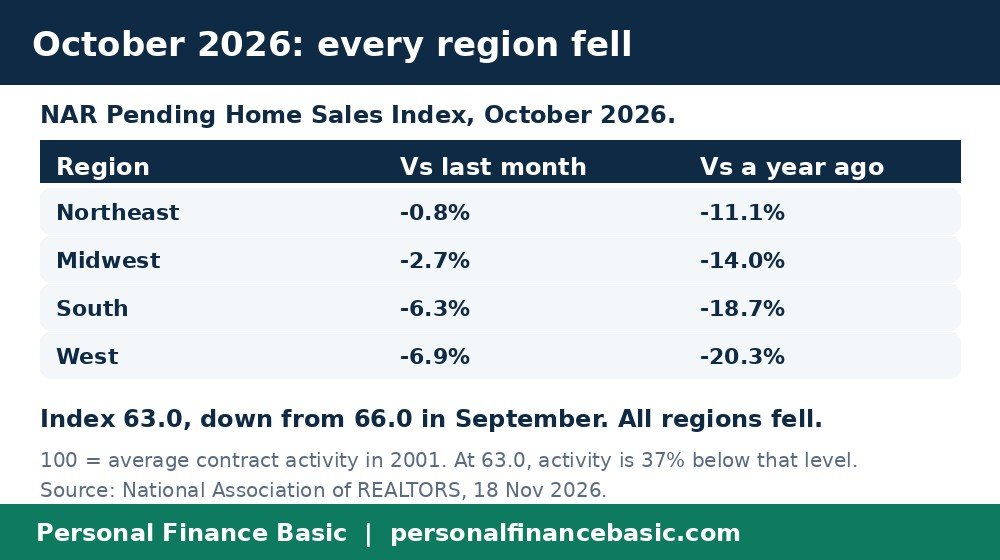
October 2026: every region fell, on both measures. Source: National Association of REALTORS, 18 Nov 2026.
Pending sales are not closed sales
The Pending Home Sales Index tracks contracts signed, not sales closed. A contract signed in October usually closes in November or December, so this report is a leading indicator of what closed sales will look like.
That is why the association’s chief economist, Lawrence Yun, warned that two straight months of record-low contracts point to very sluggish fourth-quarter closings, and annual existing-home sales could be the lowest since the mid-1990s. Last week’s closed-sales report already showed October closings at a 3.75 million annual pace, the lowest since August 2010.
Rates are the drag
The average 30-year mortgage was 7.33% in October, according to Freddie Mac, up from 6.25% a year ago. On the median home at $416,700 with 20% down, that adds about $240 a month to the payment. It has not moved much since: the weekly Freddie Mac survey put the 30-year fixed at 7.11% on 12 November, before the daily rate jumped back to 7.50% the next day.
Yun said October could mark the low point in contract signings for this housing cycle, as mortgage rates appear to have topped out. That is a possibility, not a promise. The Federal Reserve’s minutes, released the same day, pointed the other way: almost all participants judged that further rate increases would likely be appropriate in the months ahead. Do not read this report as a forecast that sales will rebound.
What it means for buyers and sellers
Buyers have more room than a year ago. Inventory rose to 1.59 million homes in October, or 5.1 months of supply, up from 4.4 months a year ago. More homes for sale and fewer buyers competing means more room to negotiate, and the record-low pipeline says competition will stay thin.
But the payment is still the problem. A $10,000 cut in the loan amount saves about $69 a month at 7.33%; a one-point fall in the rate saves about $222 a month on the same loan. The rate matters far more than the price, and it is still above 7%.
Sellers face a slower market. The typical home took 35 days to sell in October, and the pipeline of new contracts is the thinnest on record. A home priced above comparable sales will sit, so price it to the market, not to last year’s peak.
- Best for buyers right now: negotiating. With 5.1 months of supply and record-low signings, an offer below asking is more likely to be heard than a year ago.
- Not for: waiting for a crash. Nothing in this report shows prices falling, and closed-sale prices have risen for 40 straight months.
At a glance
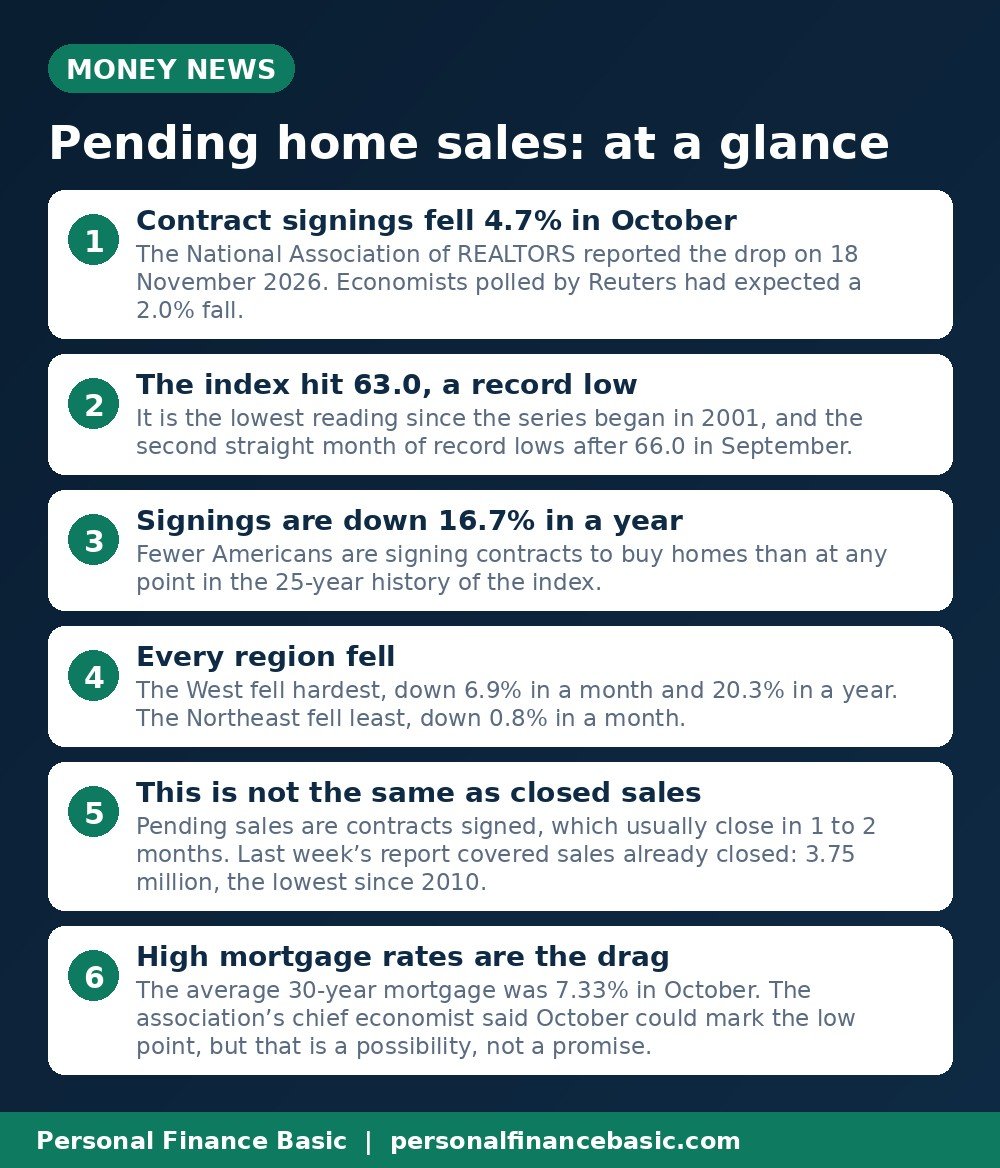
The main points from this guide, in one picture.
Frequently asked questions
What is the Pending Home Sales Index?
It is the National Association of REALTORS’ monthly measure of contracts signed to buy existing homes. A reading of 100 equals the average level of signings in 2001. At 63.0 in October 2026, activity is 37% below that average, the lowest since the series began.
How is this different from last week’s home sales report?
Last week’s report covered closed sales, at a 3.75 million annual pace in October. This report covers contracts signed, which usually close one to two months later. The first tells you what happened; the second tells you what is coming.
Why did pending sales fall so far?
High mortgage rates. The average 30-year fixed mortgage was 7.33% in October, up from 6.25% a year ago, adding about $240 a month to the payment on the median home with 20% down. Fewer buyers can afford the payment, so fewer sign contracts.
Does this mean home prices will fall?
Not on this evidence. The closed-sales report showed the median price at $416,700 in October, up 0.4% from a year ago, the 40th straight month of gains. Sales have fallen, not prices.
Is now a good time to buy?
There is no safe answer. You have more room to negotiate than a year ago, but rates are above 7% and the payment is what matters. Buy when the payment fits your budget and you plan to stay put.
The bottom line: pending home sales fell 4.7% in October to an index reading of 63.0, the lowest since the series began in 2001, because mortgage rates averaged 7.33%. Buyers have more room to negotiate, sellers face a slow market, and nothing points to a price crash. If you are buying, run the payment on your own loan amount.
This post is general education, not financial advice. Figures are from the National Association of REALTORS report of 18 November 2026 and Freddie Mac. Rates change daily, and your own rate depends on your credit, down payment and loan.
Related reading: US Home Sales Fell to Their Lowest Since 2010 — 3.75 Million in October and Mortgage Rates Fell to 7.11% — Then Jumped Back to 7.50% in Three Days